

American Eagle has been treading water for the past six months, recording a small return of 3.4% while holding steady at $17.95. The stock also fell short of the S&P 500’s 17.5% gain during that period.
Is now the time to buy American Eagle, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is American Eagle Not Exciting?
We’re cautious about American Eagle. Here are three reasons why there are better opportunities than AEO, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
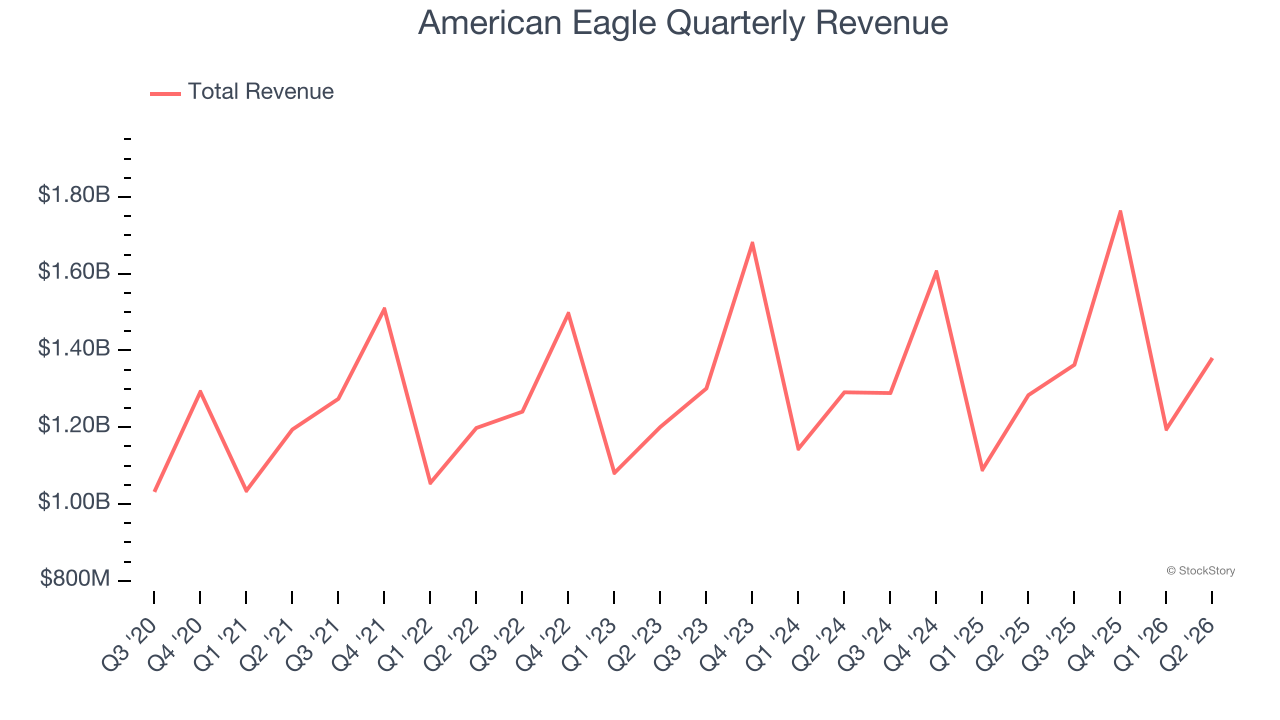
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Regrettably, American Eagle’s sales grew at a sluggish 4.3% compounded annual growth rate over the last three years. This fell short of our benchmark for the consumer retail sector.
2. Lack of New Stores, a Headwind for Revenue
A retailer’s store count influences how much it can sell and how quickly revenue can grow.
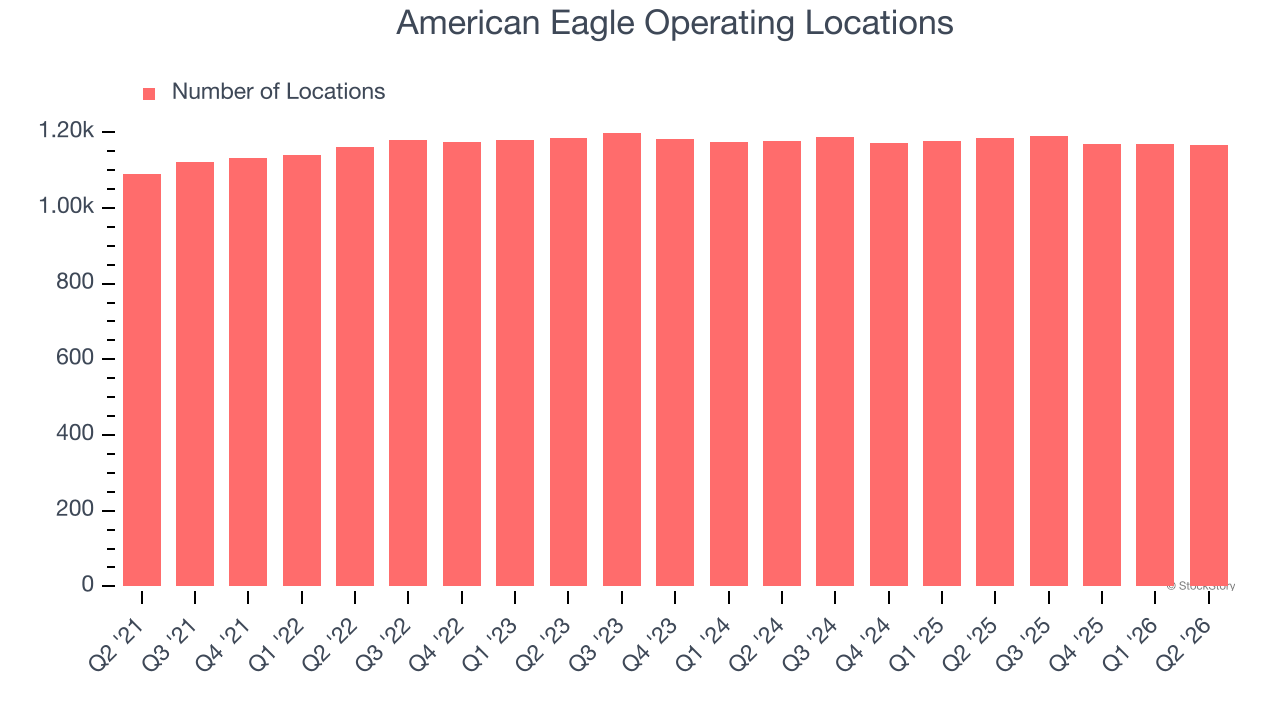
American Eagle listed 1,167 locations in the latest quarter and has kept its store count flat over the last two years while other consumer retail businesses have opted for growth.
When a retailer keeps its store footprint steady, it usually means demand is stable and it’s focusing on operational efficiency to increase profitability.
3. Previous Growth Initiatives Haven’t Impressed
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? Enter ROIC, a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
American Eagle historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 7.7%, somewhat low compared to the best consumer retail companies that consistently pump out 30%+.
Final Judgment
American Eagle isn’t a terrible business, but it doesn’t pass our quality test. With its shares lagging the market recently, the stock trades at 10.2× forward P/E (or $17.95 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re pretty confident there are superior stocks to buy right now. We’d suggest looking at the most entrenched endpoint security platform on the market.
Stocks We Would Buy Instead of American Eagle
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.