
Regional banking company WaFd (NASDAQ:WAFD) missed Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q4 2026), but sales rose 6.8% year on year to $200.4 million. Its non-GAAP profit of $0.85 per share was in line with analysts’ consensus estimates.
Is now the time to buy WaFd Bank? Find out by accessing our full research report, it’s free.
WaFd Bank (WAFD) Q3 CY2026 Highlights:
- Net Interest Income: $182.4 million vs analyst estimates of $182.9 million (9.3% year-on-year growth, in line)
- Net Interest Margin: 2.8% vs analyst estimates of 2.8% (3.3 basis point beat)
- Revenue: $200.4 million vs analyst estimates of $203.7 million (6.8% year-on-year growth, 1.6% miss)
- Efficiency Ratio: 55.1% vs analyst estimates of 54.6% (52 basis point miss)
- Adjusted EPS: $0.85 vs analyst estimates of $0.84 (in line)
- Tangible Book Value per Share: $30.51 vs analyst estimates of $31.27 (3.8% year-on-year growth, 2.4% miss)
- Market Capitalization: $2.18 billion
- Revenue is defined as net interest income plus non-interest income, less the provision for credit losses. Provision for credit losses: $20.0 million
Company Overview
Founded in 1917 and rebranded from Washington Federal in 2023, WaFd (NASDAQ:WAFD) is a bank holding company that provides lending, deposit services, and insurance through its Washington Federal Bank subsidiary across eight western states.
Sales Growth
In general, banks make money from two primary sources. The first is net interest income, which is interest earned on loans, mortgages, and investments in securities minus interest paid out on deposits. The second source is non-interest income, which can come from bank account, credit card, wealth management, investment banking, and trading fees. Regrettably, WaFd Bank’s revenue grew at a tepid 7% compounded annual growth rate over the last five years. This was below our standard for the banking sector and is a rough starting point for our analysis.
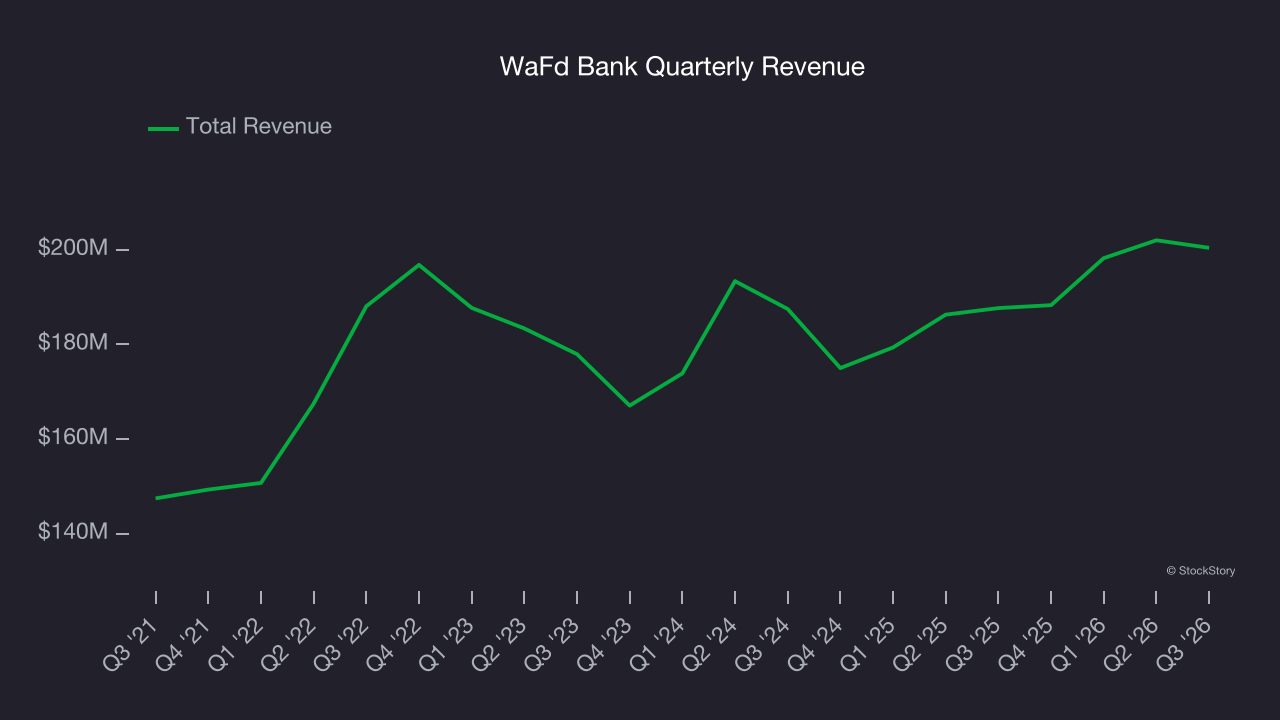
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. WaFd Bank’s recent performance shows its demand has slowed as its annualized revenue growth of 4.5% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs.
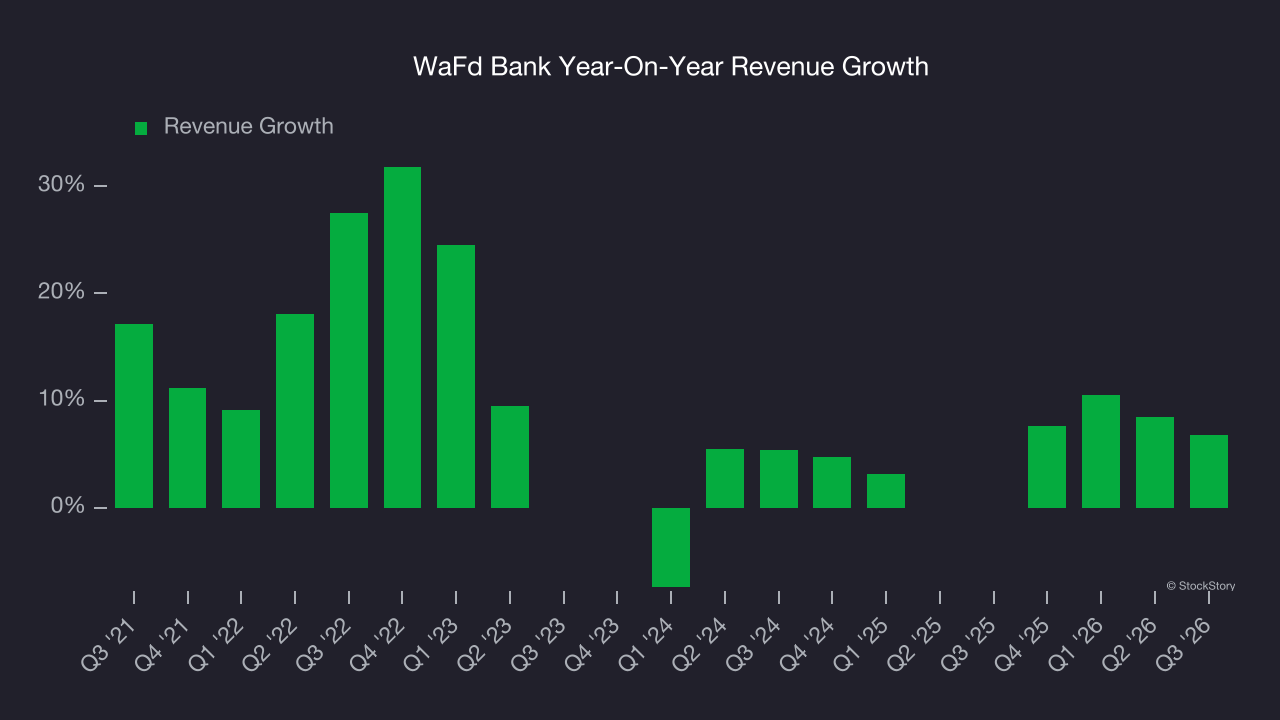
Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, WaFd Bank’s revenue grew 8.2% year on year to $200.4 million, missing Wall Street’s estimates. Revenue is defined as net interest income plus non-interest income, less $20.0 million provision for credit losses.
Net interest income made up 90.9% of the company’s total revenue during the last five years, meaning WaFd Bank lives and dies by its lending activities because non-interest income barely moves the needle.
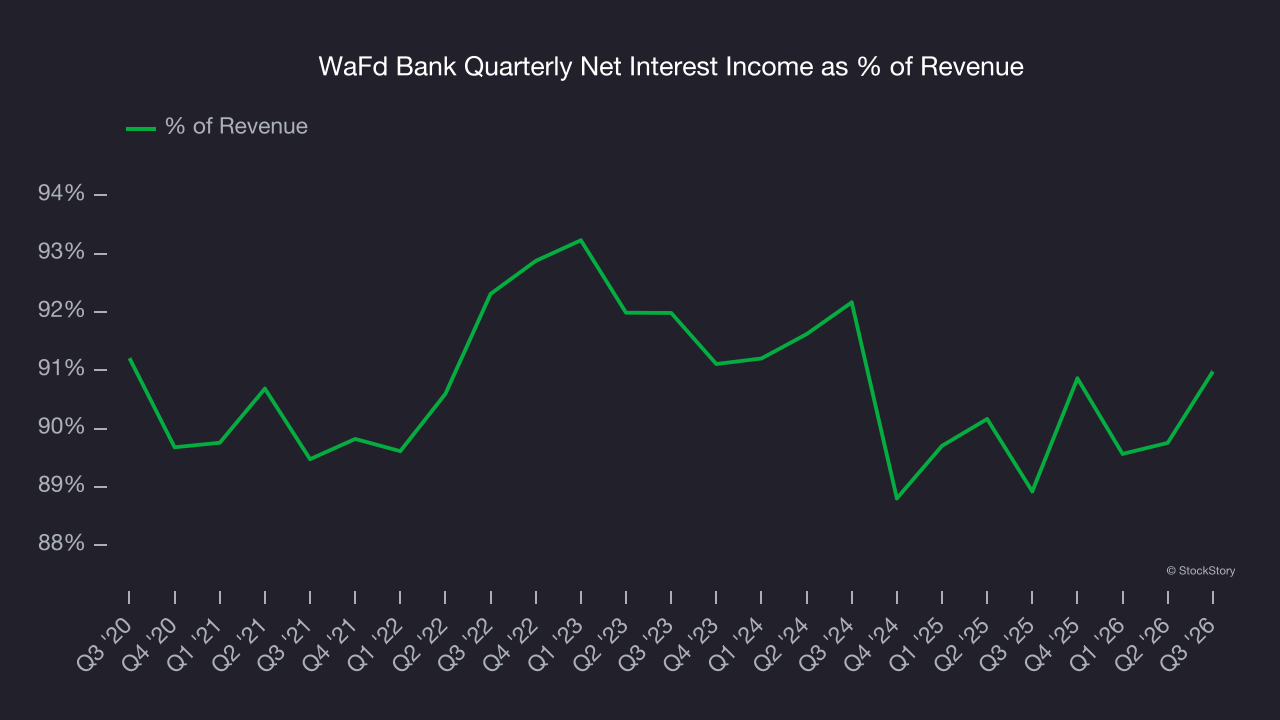
Markets consistently prioritize net interest income growth over fee-based revenue, recognizing its superior quality and recurring nature compared to the more unpredictable non-interest income streams.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Tangible Book Value Per Share (TBVPS)
Banks operate as balance sheet businesses, with profits generated through borrowing and lending activities. Valuations reflect this reality, emphasizing balance sheet strength and long-term book value compounding ability.
Because of this, tangible book value per share (TBVPS) emerges as the critical performance benchmark. By excluding intangible assets with uncertain liquidation values, this metric captures real, liquid net worth per share. EPS can become murky due to acquisition impacts or accounting flexibility around loan provisions, and TBVPS resists financial engineering manipulation.
WaFd Bank’s TBVPS grew at a decent 5.6% annual clip over the last five years. The last two years show a similar trajectory as TBVPS grew by 4.9% annually from $27.73 to $30.51 per share.
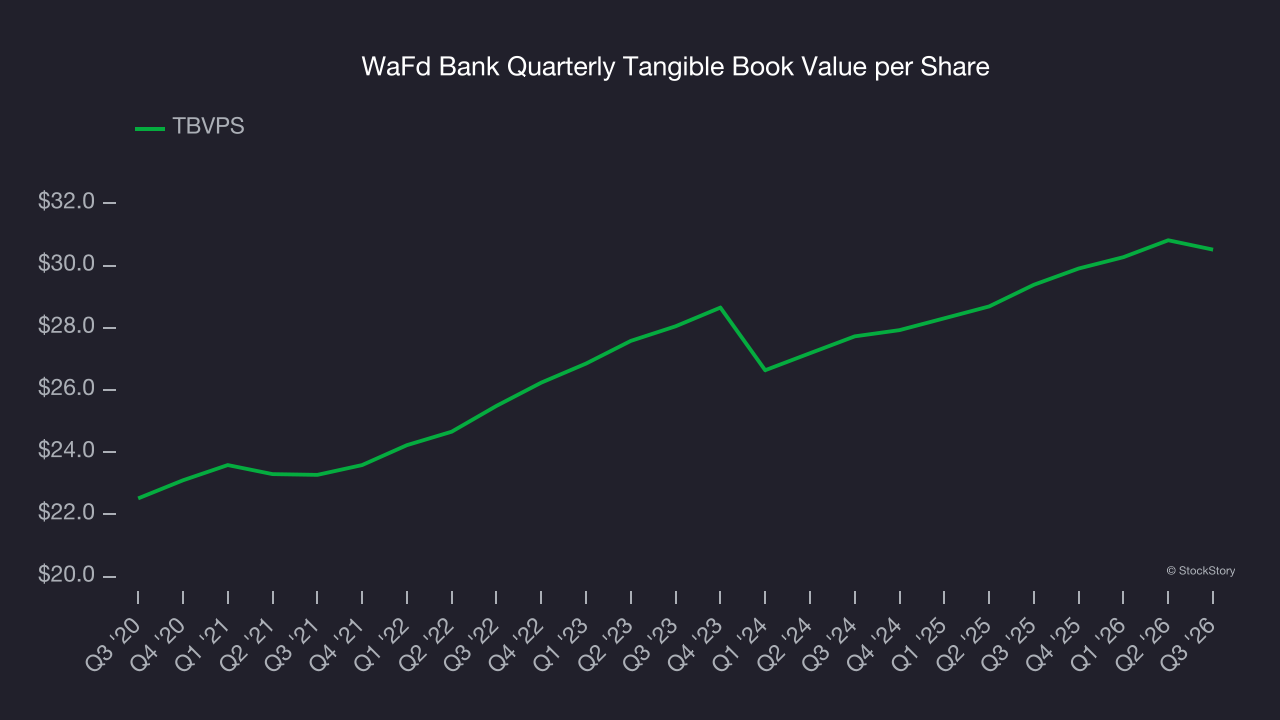
Over the next 12 months, Consensus estimates call for WaFd Bank’s TBVPS to remain flat at roughly $30.69, a disappointing projection.
Key Takeaways from WaFd Bank’s Q3 Results
We struggled to find many positives in these results. Its revenue missed and its tangible book value per share fell short of Wall Street’s estimates. Overall, this quarter could have been better. The stock remained flat at $29.63 immediately following the results.
So should you invest in WaFd Bank right now? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).