
Commercial real estate lender Ladder Capital (NYSE:LADR) reported Q3 2026 results exceeding the market’s revenue expectations, with sales up 107% year on year to $118.9 million. Its GAAP profit of $0.53 per share was significantly above analysts’ consensus estimates.
Is now the time to buy Ladder Capital? Find out by accessing our full research report, it’s free.
Ladder Capital (LADR) Q3 2026 Highlights:
- Net Interest Income: $28.83 million vs analyst estimates of $24.08 million (3.7% year-on-year growth, 19.8% beat)
- Revenue: $118.9 million vs analyst estimates of $77.26 million (107% year-on-year growth, 53.9% beat incl $65.6 million of net gains on real estate, a figure that was zero in the previous quarter and same quarter last year)
- EPS (GAAP): $0.53 vs analyst estimates of $0.14 (significant beat incl $65.6 million of net gains on real estate, a figure that was zero in the previous quarter and same quarter last year)
- Market Capitalization: $1.12 billion
Company Overview
Founded during the 2008 financial crisis when traditional lenders retreated from commercial real estate, Ladder Capital (NYSE:LADR) is a real estate investment trust that originates commercial real estate loans, owns commercial properties, and invests in real estate securities.
Sales Growth
Two primary revenue streams drive bank earnings. While net interest income, which is earned by charging higher rates on loans than paid on deposits, forms the foundation, fee-based services across banking, credit, wealth management, and trading operations provide additional income. Unfortunately, Ladder Capital’s 9.2% annualized revenue growth over the last five years was mediocre. This fell short of our benchmark for the banking sector and is a tough starting point for our analysis.
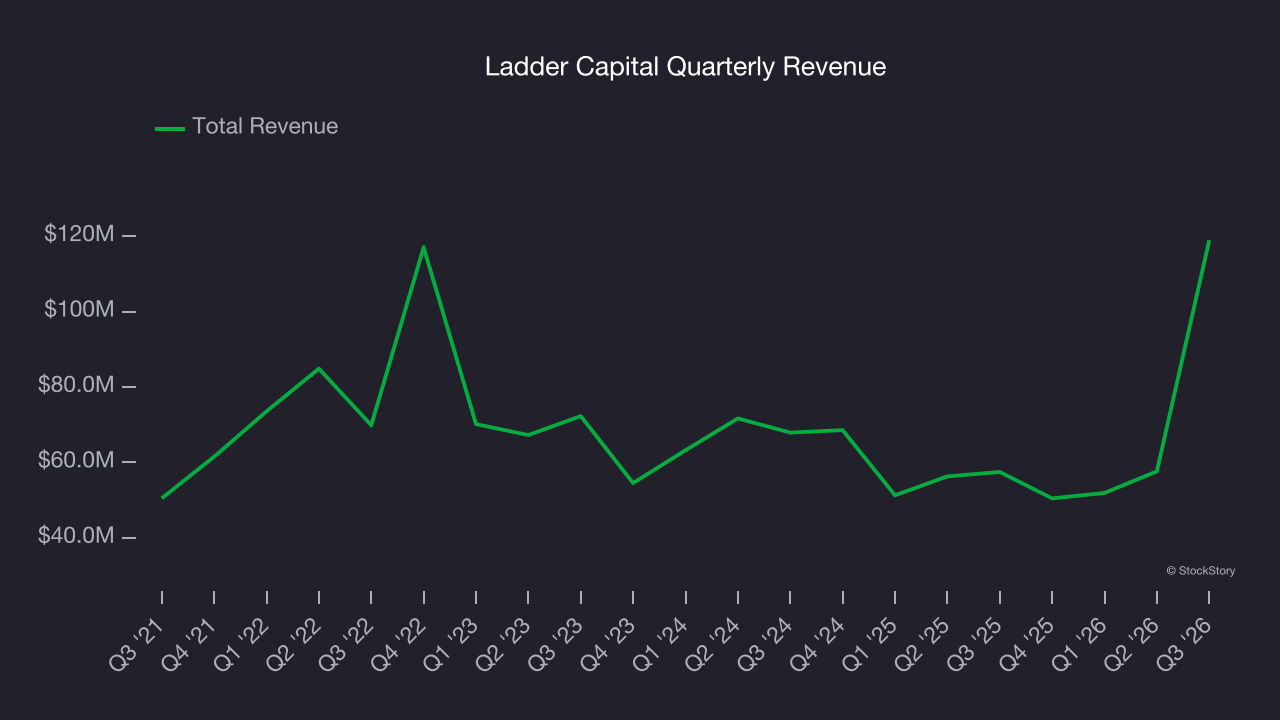
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. Ladder Capital’s performance shows it grew in the past but relinquished its gains over the last two years, as its revenue fell by 8.1% annually. 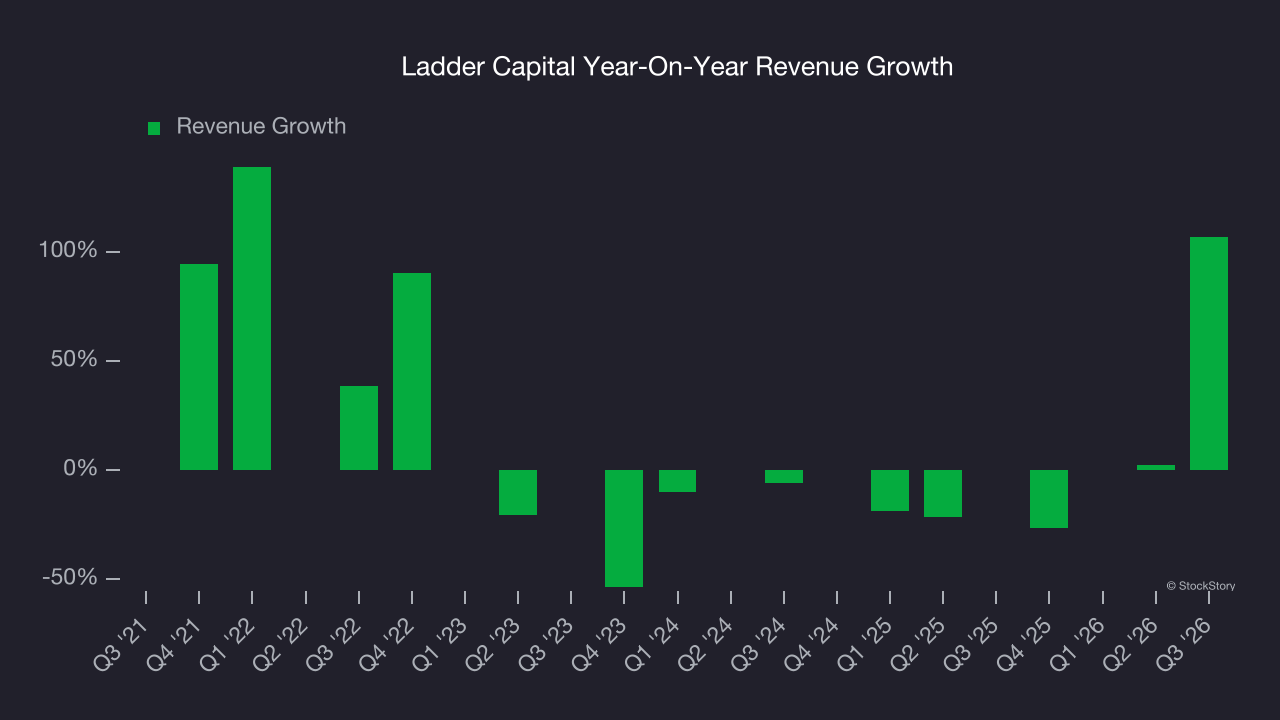 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Ladder Capital reported magnificent year-on-year revenue growth of 107%, and its $118.9 million of revenue beat Wall Street’s estimates by 53.9%.
Net interest income made up 42.9% of the company’s total revenue during the last five years, meaning Ladder Capital’s growth drivers strike a balance between lending and non-lending activities.
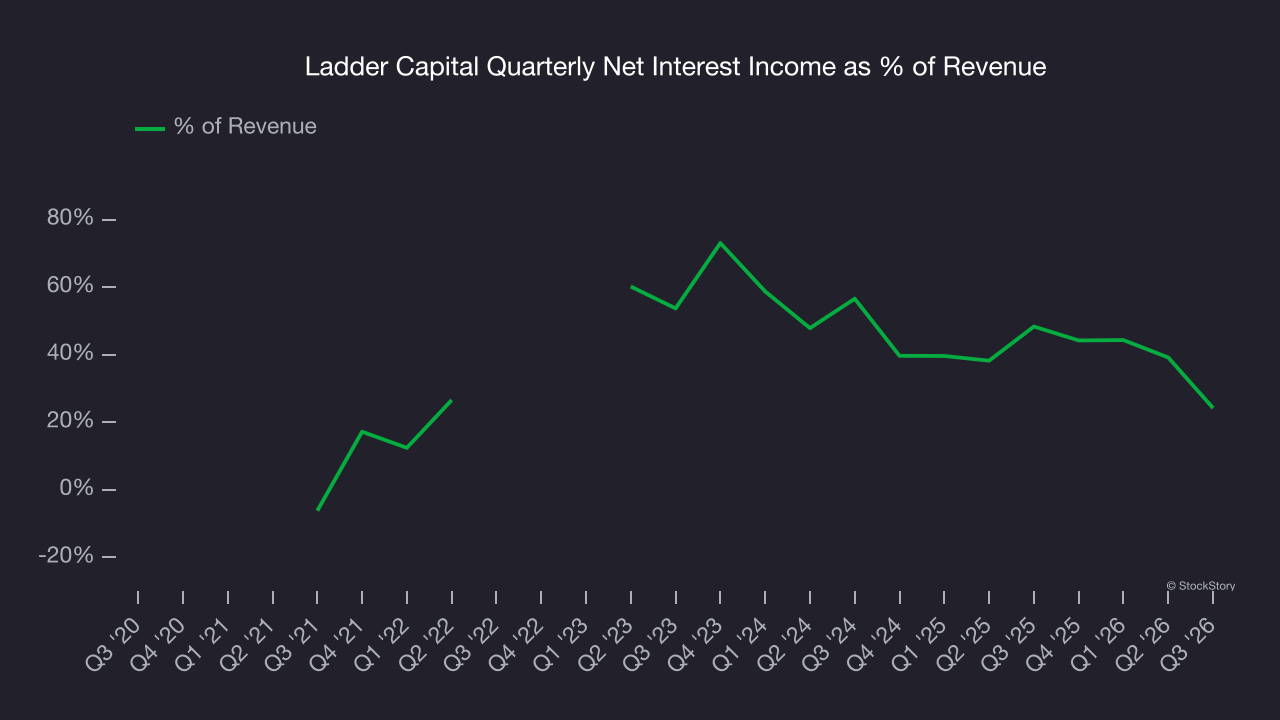 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
Net interest income commands greater market attention due to its reliability and consistency, whereas non-interest income is often seen as lower-quality revenue that lacks the same dependable characteristics.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Key Takeaways from Ladder Capital’s Q3 Results
It was good to see Ladder Capital beat analysts’ net interest income expectations this quarter. Revenue and EPS also beat, but this included $65.6 million of net gains on real estate, a figure that was zero in the previous quarter and same quarter last year. Zooming out, we think this was a solid print. The stock traded up 3.4% to $9.14 immediately following the results.
Indeed, Ladder Capital had a rock-solid quarterly earnings result, but is this stock a good investment here? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).